After the restructuring process, the worst aspects for Nam Kim Steel seem to be behind.

According to the evaluation by Ho Chi Minh City Securities Corporation (HSC), the worst aspects for Nam Kim Steel ( HOSE: NKG) seem to have passed as the Company’s Leadership successfully restructured its business operations.
Specifically, NKG focused mainly on internal activities, reorganizing customer tiers, inventory systems, production, and enhancing cost management.
HSC forecasts that NKG’s core business segments will gradually return to growth from the first quarter of this year following determined restructuring efforts since early last year, involving asset sales, management changes, and the introduction of new business strategies.
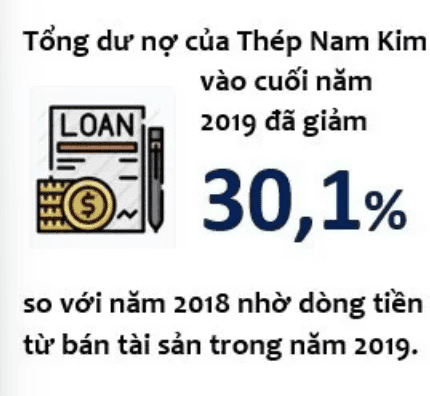
Cash flow from asset sales in 2019 also allowed NKG to reduce its debt. The company’s total debt at the end of 2019 decreased by 30.1% to 3,092 billion VND. Consequently, interest expenses also decreased by 8.7% to 309 billion VND in 2019.
The company also successfully reduced raw material input costs, and gradually changed its inventory policies. HSC indicates that NKG will maintain a policy of only one-month raw material inventory, and one-month finished product inventory.
The company’s leadership stated that NKG will no longer engage in speculation on raw materials (inventory up to 2.5-3.0 months of production) as it did in the past (2017-2018) to minimize the risk of fluctuations in input material prices (HRC).
Internal cost management is another priority of the new Board of Directors, with more involvement from SMC (a steel distribution company holding 5% of NKG’s shares), which is a positive signal for NKG to address long-standing operational issues.
HSC believes that after addressing many operational issues, inventory strategies, and cash flows, 2020 is expected to be a promising year for NKG after two years (2018-2019) of declining profit pressures. Additionally, with ongoing efforts towards restructuring, the company no longer finds it necessary to increase its charter capital at this stage.
However, HSC also assesses prolonged oversupply in the galvanized steel segment, and increasing competition as concerns for the entire industry, and specifically for NKG.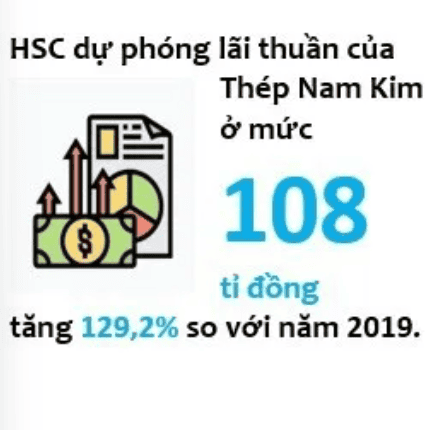
Many businesses entering the industry have increased pressure on selling prices, and affected profitability ratios.
The restructuring process in the industry continues, and it will take several more years for the market to balance. Meanwhile, export activities still face trade barriers such as anti-dumping duties, and weakened demand due to COVID-19.
With thin profit margins, any fluctuation in input materials (HRC) will significantly impact NKG’s profitability.
Therefore, HSC estimates that NKG will only record modest profits in the first quarter of this year. However, compared to a loss of 101.6 billion VND in Q1.2019, this modest profit figure for the same period this year still reflects the success of the company’s restructuring.
For the whole year 2020, HSC forecasts NKG’s revenue at 11,991 billion VND, and a projected profit of 108 billion VND, representing a growth of 129.2% compared to 2019.
Source: Nhip Cau Dau Tu Newspaper
Link: https://nhipcaudautu.vn/tai-chinh/thep-nam-kim-duoc-gi-sau-khi-tai-co-cau-3334468/